charmainsaaved
About charmainsaaved
5 Methods Realestate Will Make it easier to Get Extra Business
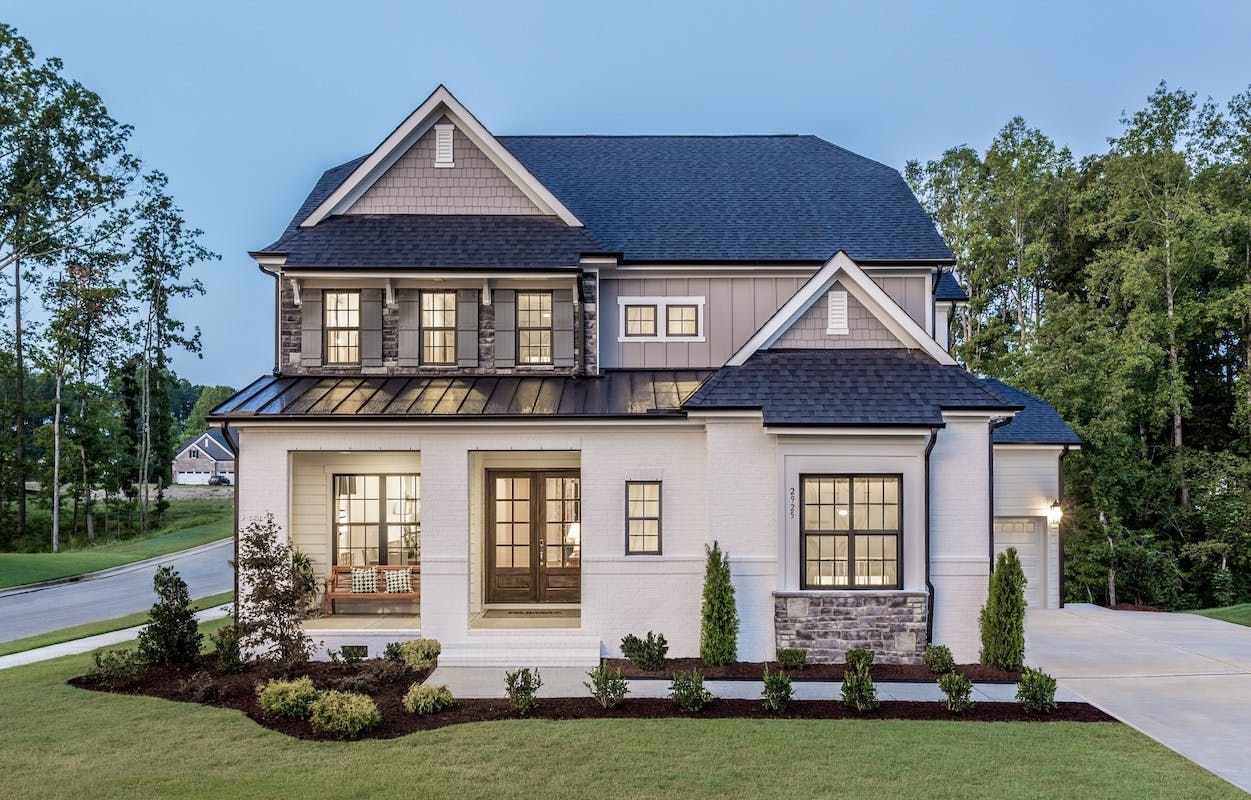 Every few years the housing market rewrites the rules, and buyers who learned the last set of rules show up unprepared for the new ones. Right now, the rules have changed more than they have at any point in a generation. The buyers who understand that are finding deals. The ones who do not are making expensive mistakes.
 The arithmetic here is brutal and worth understanding clearly. A buyer who financed a $400,000 home at three percent in 2021 pays roughly $1,686 per month on principal and interest. That same loan at a seven percent rate costs $2,661. Those numbers explain why the market froze rather than crashed when rates moved higher. Volume collapsed. Prices mostly did not.
Here is what that creates for someone with solid credit and a real pre-approval in hand: a better chance of getting the house you want without losing a bidding war. The panic buyers are gone. The buyers who showed up with letters waiving inspections and offering a hundred thousand over asking have mostly sat back down. What remains is a more functional market, even if it is not a cheap one.
 Shop at least three lenders before you commit to one. A 0.25 percent gap between two lenders’ quotes adds up to around twenty thousand dollars over a thirty-year loan on a four hundred thousand dollar mortgage. Lender fees vary too. Do not compare rate quotes without also comparing origination fees, points, and closing costs.
If the report surfaces problems that go well beyond normal wear and tear, you have three options, not one, and walking away is a legitimate one of them. You can ask the seller to repair specific items before closing. What you should not do is panic and waive your right to negotiate.
 Budget enough to cover origination fees, title, escrow, prepaid taxes, and insurance without being caught short at the table. First-time buyers often do not see the full closing cost picture until the Closing Disclosure arrives three days before settlement. Ask your lender for a Loan Estimate with a realistic purchase price so the numbers reflect what you are actually going to face.
The timing question, whether to buy now or wait for a better moment, is the one that trips up more buyers than any other single factor. No one consistently times the real estate market. The more useful question is not whether now is the right time in the abstract; it is whether the home works for your actual life for the next five to seven years.
The buyers who come out ahead in this market are not the ones who waited for perfect conditions. They are the ones who got their finances in order early. If you are ready to take that step, real estate listings and buyer tools are a practical starting point.
No listing found.